Real Estate

How to Stage Your House Over the Holidays

By Guest Blogger
November 11, 2015
This was originally published on the official blog of Century 21® on November 3, 2015 *

Selling your home during the holidays doesn’t mean you have to hold back on the festivities. Let your home shine while attracting buyers during the most wonderful time of the year with these seasonal touches.

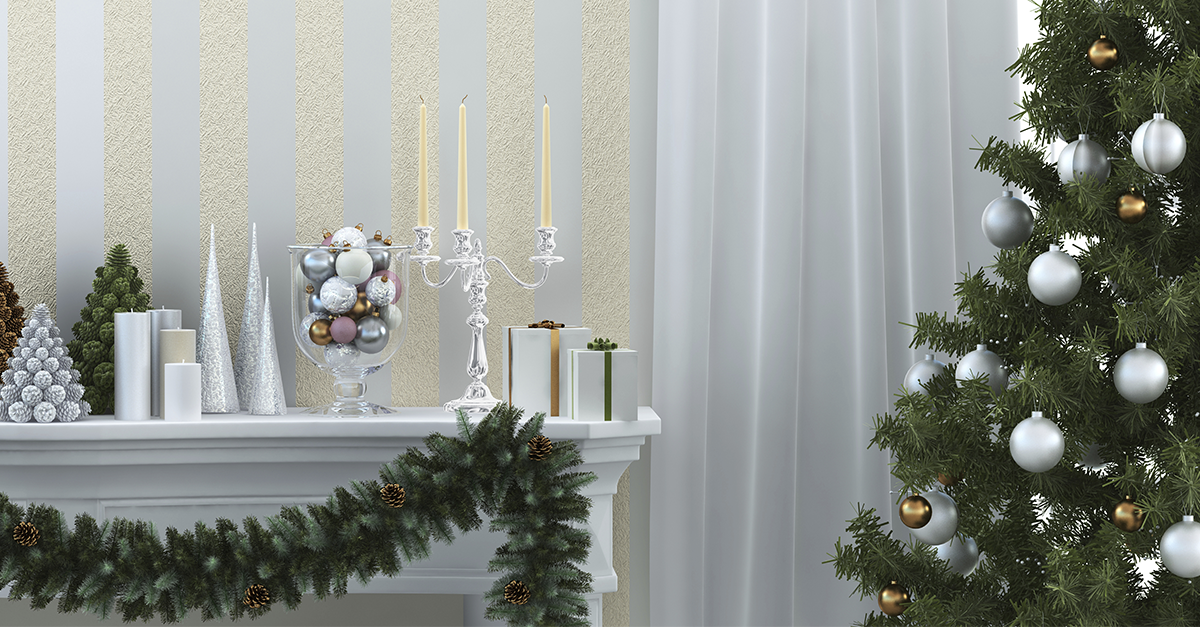
HolidayStagingBlogPic

Deck the halls:

Don’t let selling your home stop you from spreading the holiday cheer. Subtle hints like a welcoming evergreen wreath at the front door, mulled cider brewing on the stovetop or hand-sewn stockings hanging from the fireplace awning gives the space a jolt of spirit.

Trim the tree:

Usually the most eye-catching piece of the living room during the holiday season, make sure your spruced-up Christmas tree matches the aesthetic you want to sell to potential buyers. If your living room has a clean-cut scheme with ivories and whites, for example, make sure your baubles fall under the same color palette.

Tone it down:

As tempting as it is to blow up some lawn ornaments to celebrate the season, it’s best to go for a minimalist approach during this crucial selling time. Neatly highlight the defining elements of your home’s exterior with snow-white lights or hang a fresh garland with bright red bows from your rooftop or mailbox.

Warm up:

Before open houses, make sure your home feels as cozy as possible. Now’s the perfect time to light a fire in your fireplace and warm up your home. If your home is lacking the fiery centerpiece, turning up the thermostat to a comfortably toasty level gives potential buyers extra incentive to linger for a while to escape the brutal cold outside—and allows them to fully digest the best qualities of your home.

Tune up:

Fill up the hallways with contemporary holiday classics while potential buyers are roaming the halls. Make a mix of festive favorites: go old-school with Frank Sinatra’s “White Christmas” or Natalie Cole’s take on “The Christmas Song”…or just play Mariah Carey’s “All I Want for Christmas (Is You)” on a loop.

Feed the masses:

The best way to make somebody feel at home—potentially at their future home—is through their stomach. Whip up some holiday-themed cookies and mocktails to serve during your open house; the extra hint of hospitality will keep you in the mind of prospective buyers even after the last present is unwrapped during the holidays.

*Article reprinted with permission of Century 21 Real Estate LLC.

5 Places You Forgot Potential Buyers Will Check

By Guest Blogger
October 15, 2015
This was originally published on the official blog of Century 21® on October 14, 2015 *

An open house is a crucial component of the home sale process. Start with these tips for staging an open house, but don’t stop there. Potential buyers are likely to inspect all areas of the house. Yes, even your “junk drawer” and closets. Here’s a list of five often forgotten places that potential homeowners may check.

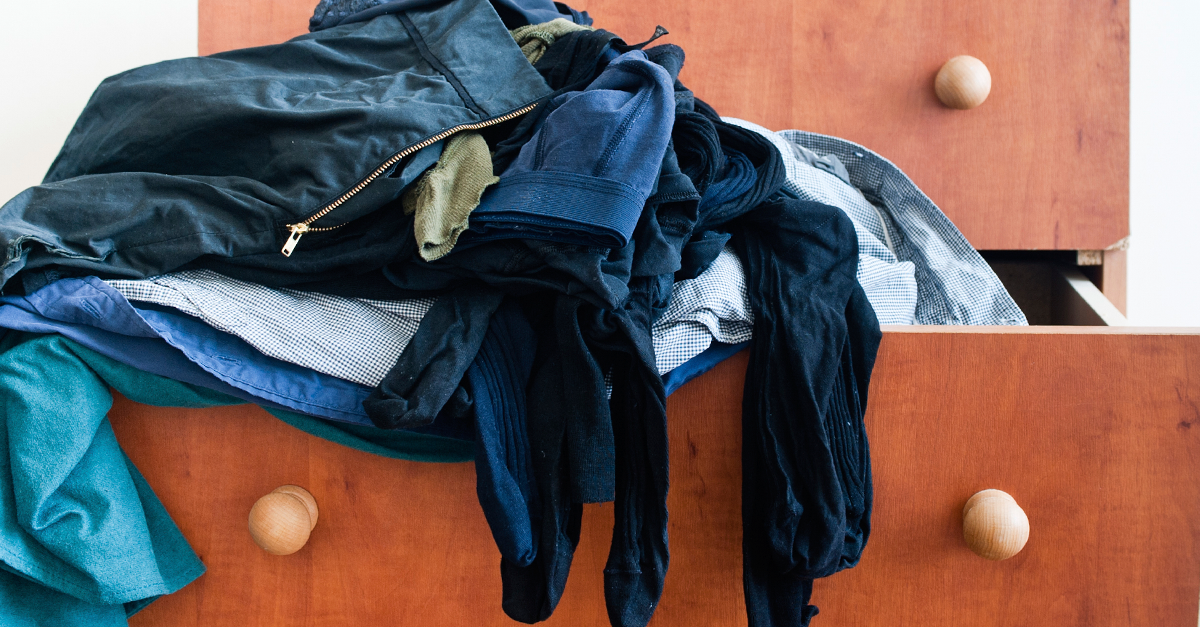
C21_Oct_Batch1_Blog-Closet

The sides of your house

When you spruce up your front yard and backyard, pay attention the sides of your home as well. Potential buyers will likely look at the exterior of your house from all angles. One unkempt side may turn them off from the rest of the home. Make sure the paint and landscaping is in good condition from all angles.

Inside your closets

Don’t stuff everything in your closets and hope no one will open them. Even if the potential buyers aren’t fashionistas, they may still care about closet space. Show it off by organizing it. You wouldn’t want a potential buyer to open a closet just to find a hodgepodge of the belongings you stashed there.

Under your bed

Removing the bulk of storage from your closets is a great way to make closet space appear bigger, but that doesn’t mean your stuff should be shoved under the bed. Not only is it an eyesore, but the potential homebuyer might also see it as a sign that there is not enough storage space. Your best bet is to invest in temporary external storage space so that your open house has all the space it needs.

Inside the shower

Chances are no one wants a small, cramped bathroom. Create storage solutions that may make your space appear bigger and brighter to buyers. For example, stash toiletries and cleaning supplies in a separate closet, a dresser, or under the sink.

Your drawers and cabinets

Potential buyers will probably open drawers and cabinets. Spend time getting inspired by these home organizers. Think about all of the details like your spice rack, whether your dishes match, and finally taming your “junk drawer.” In need of more inspiration? Our Pins may help!

Go the extra mile, and don’t get caught off guard. You wouldn’t want to scream a slow motion “nooooo” as a potential buyer innocently reaches to open a closet.

*Article reprinted with permission of Century 21 Real Estate LLC.

Dealing With Multiple Offers

By Jim Stearman, Attorney at Law
August 27, 2015

In a hot real estate market, it is not uncommon for multiple offers to flood into the listing agent’s inbox. Effectively dealing with multiple offers is the sign of a good agent who is looking out for the best interests of his or her sellers. When you receive multiple offers, it is wise to get your manager involved. If a mistake is made, your clients may be put in the position of selling their house twice so you should take the extra step of protecting you and your clients before they start making phone calls to you to find out what went wrong.

By making a counter offer to all offers received, accusations of discrimination or unfairness can be avoided. The sellers, of course, have the option of accepting one of the offers or negotiating with only one or two of the buyers but, in most cases, issuing a counter offer to all prospective purchasers will usually result in a better price for the sellers.

Couple_WFAgent9

To avoid selling the house twice, it is recommended that you use C.A.R. Form SMCO, Seller Multiple Counter Offer, when counter offers are going to be made to multiple offers. This form contains the necessary language to protect the sellers by informing the buyer that sellers are making multiple counter offers to other prospective buyers and that certain conditions must be met by the buyers for the counter offer to be deemed accepted. Many agents feel that you should not counter back on price but, instead, should ask all buyers to bring back their “best offer”. At that point, the sellers would hopefully be in a position to accept at least one of the multiple counteroffers. You can always negotiate upon terms other than price but you may lose buyers if your sellers counter with another price in response to the buyer’s “best offer” price.

When you’re representing the sellers of a home that will likely receive multiple offers, you can really help them out by getting them ready to make a good decision. Some of the things that could help them would be a review of their financial situation and to find out what is important to them. It could be that your clients would rather receive a lower offer with no contingencies that will close quicker than a higher priced offer that won’t close for several months. Just remember to tell your clients that you are there to guide them through the process and to help them get the result that is best for them but that they are the ones that will ultimately make the decision on which offer is best for their needs.

DISCLAIMER: This article has been prepared for general information purposes only. The information in this article is not legal advice. Since legal advice is dependent upon the specific circumstances of each situation, please contact an attorney for a consultation on your matter if you have any questions.

About the author: Jim Stearman is an attorney in North Orange County, California with over 35 years of experience. His areas of expertise include real estate transactions, general civil law disputes, business and commercial transactions, partnership law, corporate law and enforcement of judgments and collections. For more information about Mr. Stearman please visit his website www.jamesstearmanlaw.com.

Mobile Apps for Real Estate Agents

By Stephanie Goedl
July 30, 2015

Mobile  Apps….what would we do without ‘em? As REALTORS® we have a multitude of apps to help us in our business. Here are some of my favorites that I recommend to the agents in our office:

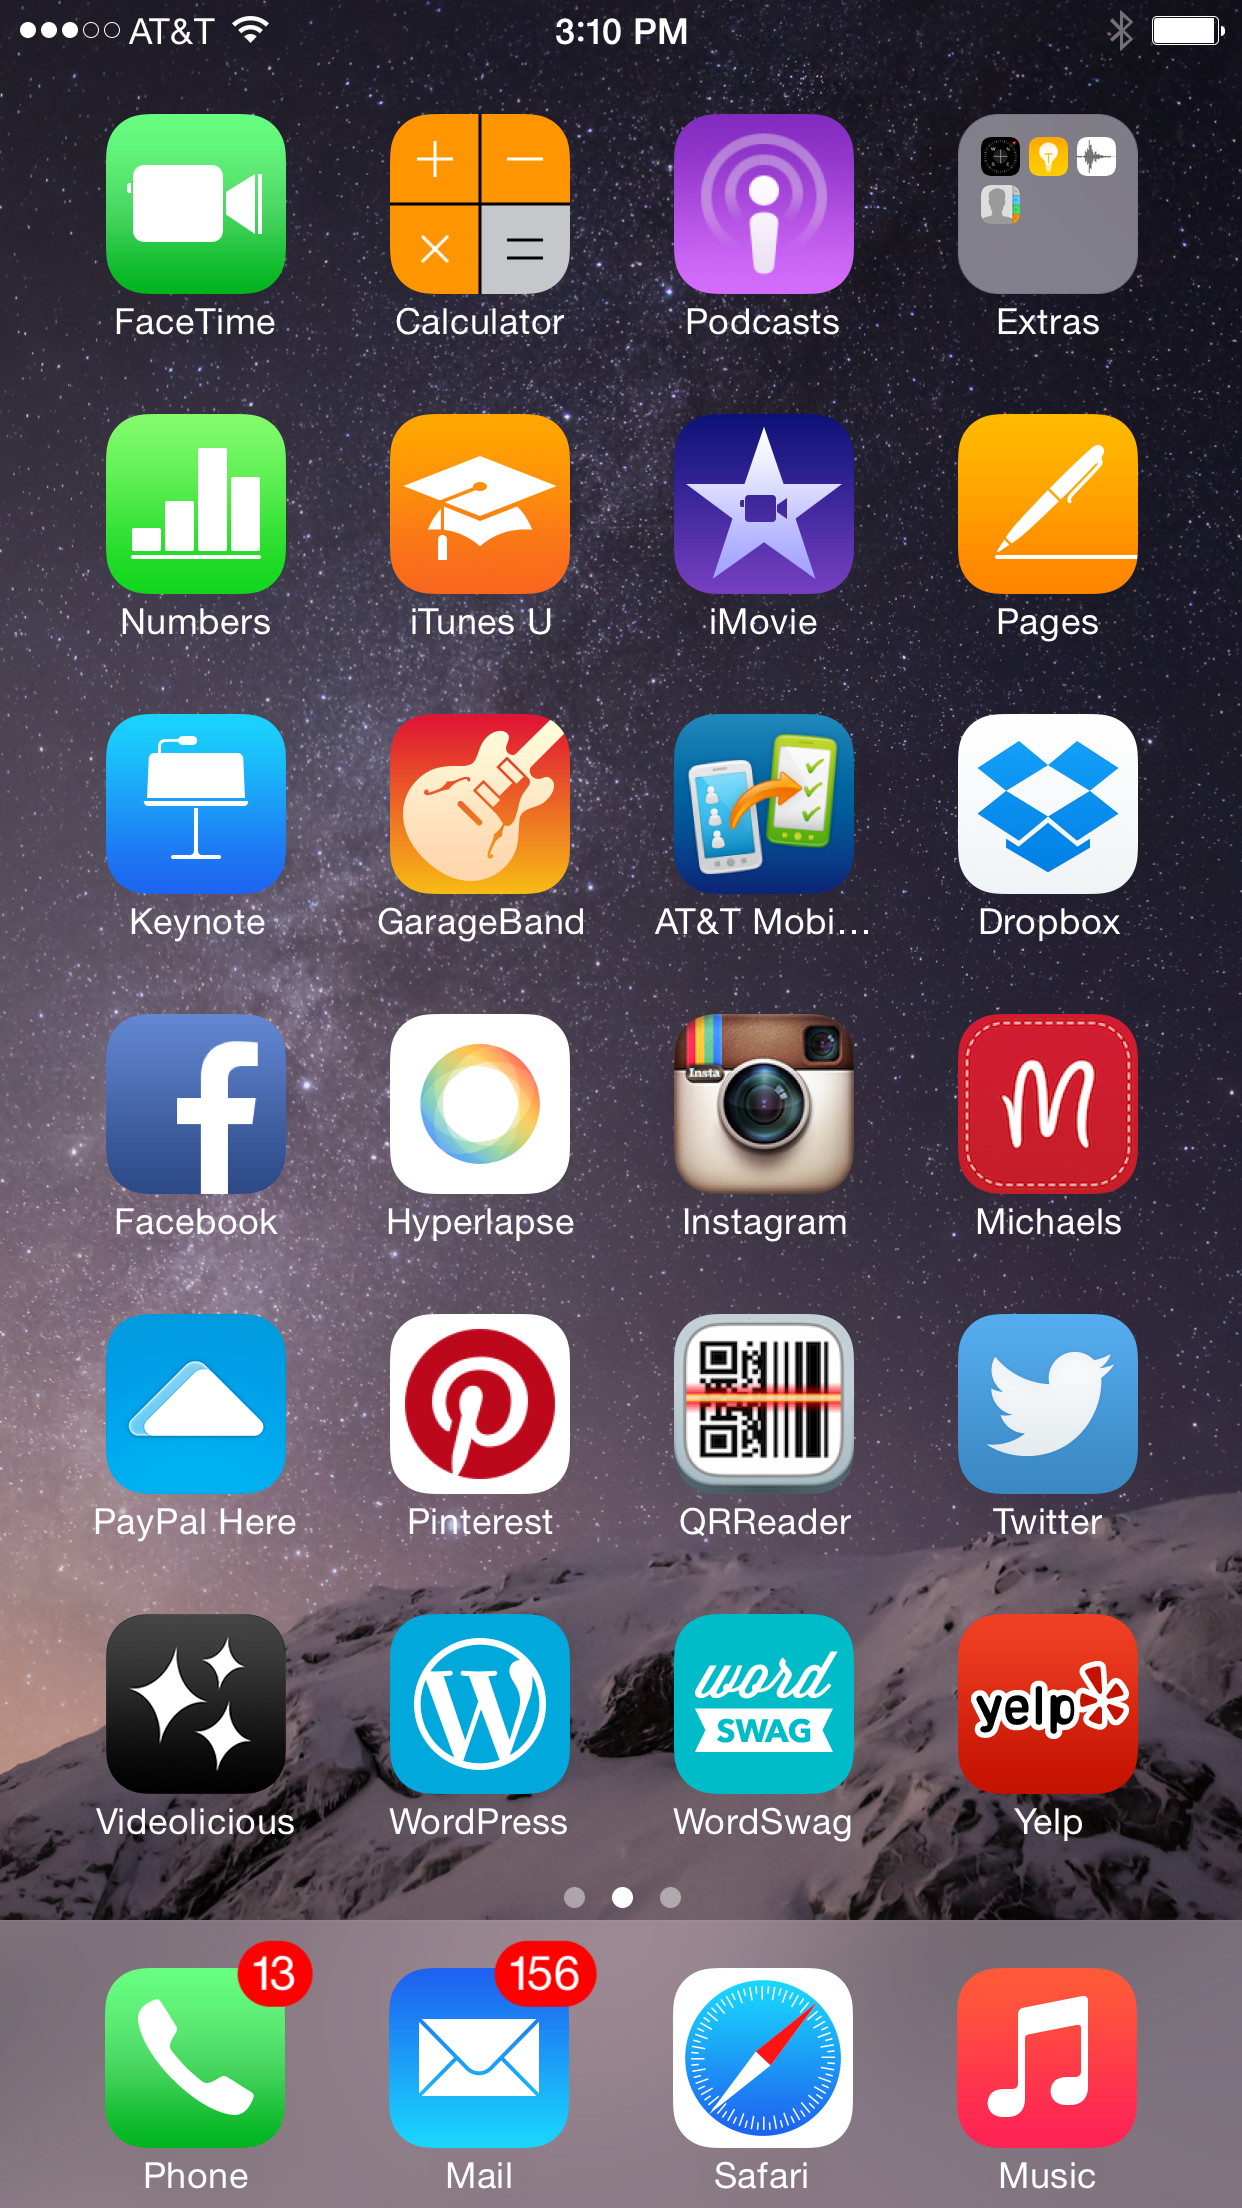
MobileApps

Open Home Pro
This app that you download to your tablet device allows you to capture contact info of the visitors that come into your Open House. After you upload photos of the home into the app it provides a slide show of the property for your open house visitors to view. It also has a feature that allows you to automatically send a thank you email to that lead after they leave the Open House. I suggest you place the tablet with slide show running on the counter or dining table near the entrance so visitors can sign in.

Videolicious
This app allows you to create and edit videos on your iPhone or iPad. You can email the video directly from the app or publish to Facebook, Twitter or YouTube.  With this user-friendly app you can create agent profile videos, client testimonial videos and property or community videos. They have an amazing customer support team that responds quickly to email questions. It’s a great way to connect with your clients via video.

Dropbox
This service allows you to take your documents, files, photos & videos anywhere and share them easily with other people. This service is available as a desktop and a mobile app so you can access it anywhere.  The nice part about this app is that it lets you share files that would be too large to email. Dropbox offers 2 GB for free. You can purchase more storage space if needed. This is a must for professionals on the go.

Typic
This app allows you to add filters, effects and text to photos.  My favorite feature is the ability to add your logo to the photo for a small upgrade fee. This is great if you are using photos across multiple social media platforms. Your photos will have your logo embedded on them and will look like they were professionally done.

Below is a short video with an overview of 4 additional apps that will help you in your business.

MobileAppVideo

About the author: Stephanie Goedl is the Chief Operating Officer of CENTURY 21 Discovery. For more information about CENTURY 21 Discovery you may call (714) 626-2000.

The #1 Threat to Real Estate Industry

By Joe Lins
June 29, 2015

The National Association of REALTORS® (NAR) recently released the D.A.N.G.E.R. Report which stands for Definitive Analysis of Negative Game Changers in Real Estate. You can download a copy of the report HERE. NAR commissioned Swanepoel | T3 Group, an outside management consulting firm, to conduct an analysis of the threats, opportunities and trends in the real estate industry.

While there were many threats to the industry and our profession from outside the industry, there was one huge threat mentioned in the 160+ page report that comes from within the industry. According to the DANGER Report, the #1 threat to real estate professionals and the industry as a whole are other agents who are unqualified and/or incompetent. The Report says, “The real estate industry is saddled with a large number of part-time, untrained, unethical, and/or incompetent agents. This knowledge gap threatens the credibility of the industry.”

DangerSign2

The Report cites the low state requirements to become a licensed real estate agent. The national average to get a license requires a measly 70 hours of training. Having the bar set so low to enter the profession or even remain in this profession is a recipe for trouble. Agents are allowed into the business with a very basic knowledge. That’s okay, you have to start somewhere. The problem is the brokers who hire these agents without providing any additional training or oversight and just letting them loose on the streets.

I see it firsthand every day. In California we have many forms and requirements that are constantly changing. What happens when the broker does not provide the ongoing supervision or training or insist the agent get it from through their local association? I can tell you from experience with agents from other firms, at times it isn’t pretty.

We recently had a new Residential Purchase Agreement (RPA) roll out in California. Our Executive Leadership team knew it was coming and prepared our agents over the course of several months by providing training on the new RPA. About a week after it went into effect, I got a phone call from one of our agents who was in a transaction with an agent from another firm. That agent knew nothing about the new RPA and didn’t know how to complete it. Our agent asked if we would be willing to train the other agent on the new RPA. I said “Absolutely!” A well-trained agent is good for everyone involved including the industry.

I’m not looking forward to the roll out of the new TRID requirements later this year. Not because it’s a new requirement. We’ve been talking to our agents about this for weeks and they will be receiving training so they are ready for the change. I’m dreading it because I know that most agents on the other side of the transaction will not have a clue. When that happens the person who will be the most vulnerable and frustrated will be the client. Their dissatisfaction is a negative impact on our profession and industry.

Yes, the training to become a license real estate agent is minimal. That is why it’s up to each broker and real estate association to have higher requirements to be affiliated with them. Every market and state is different but there needs to be a consensus from the leaders in this industry to raise the bar and hold the Brokers who don’t, accountable.

For those of us who believe this is a true profession and one that we consciously chose, this should be a no-brainer.

Joe Lins photo


About the author: Joe Lins is President and Co-owner of CENTURY 21 Discovery. If you are interested in becoming part of the CENTURY 21 Discovery team contact Joe at 714.626.2069.

Creatively Saving For A Down Payment For Your First Home

By Shantell Lorraine Nicole Russell of New American Funding*
June 8, 2015
Originally Published on June 4, 2015

moneyNAFblogRental rates are quickly rising making it more difficult to continue affording an apartment. While purchasing a home might seem like a less expensive option, saving for a down payment on a house is likely one of the more difficult aspects of becoming a home owner. One of the common standards for a down payment is 20 percent of the total value of the home. This can add up quickly and between mountains of student debt and the entry level job market, setting aside funds can be a challenge. However, with more lenient lending standards and a few tricks, you can start saving and become one step closer to owning a home of your own.

Understand the importance of a down payment
Before you begin planning to save up some extra cash, know how a down payment impacts your ability to become a homeowner. A down payment is the money you put toward a home right away. Zillow noted that the amount you can contribute upfront can impact the type of home mortgage you qualify for and ultimately how much house you can afford. In addition, your credit score and income also contribute to the home loan you ultimately receive.

This can help you determine how much you want to save for your future home. If you would like to purchase a more expensive home, but do not have the credit score or annual income to support higher monthly mortgage payments, providing a larger down payment can help ensure you still can afford a home more congruent to your preferences. Additionally, paying less than 20 percent of the total value of the home may mean that you need to also pay mortgage insurance on a regular basis.

Mortgage insurance is a way to back up a loan in case you are unable to make payments due to your financial circumstances.

Options for low down payments
If you are interested in acquiring a home without spending a great deal of money up front, Freddie Mac and Fannie Mae, government-backed lenders, both offer loans with 3 percent down payment options.

First-time homebuyers may qualify for these affordable options depending on their ability to provide specific information and meet certain standards to avoid underwriting mortgages. For example, Freddie Mac mandates that applicants can cover the closing costs as well as the full down payment agreement. Additionally, homebuyers must enroll in a borrower education program similar to the one offered by Freddie Mac. Fannie Mae also implemented similar requirements to combat lending money to an unsuitable candidate who is unable to afford a home.

Techniques for saving money 
After deciding how much money you wish to save for a down payment, USA Today recommended setting up automatic contributions to your savings account every pay period. This ensures that you are not tempted to dip into your pot and spend any of your money before putting it into your savings account. In addition, automatically sending money to your savings account is a great idea as long as you have properly budgeted for a specific amount to be contributed regularly.

Developing an adjusted budget to accommodate your new efforts is an important step to the process. Decide how much money you need for your expenses, like rent, bills, food and any debt. Then allot additional money for recreational spending.

The Daily Finance also noted it might be a smart idea to keep your savings safely stored away somewhere that it is more difficult for you to access. Consider starting a high-yield savings account or CD.

Know where to make cuts
There are a number of frivolous expenses that can add up and prevent you from saving for a down payment on a house. Below are some extra expenses you might consider reducing to help increase your savings:

  • Making daily coffee shop runs
  • Eating out regularly
  • Going out to the bars
  • Going to the movies
  • Taking weekend trips
  • Having regular manicures or pedicures
  • Attending concerts, plays and other performances


Add additional income

If you are ready to purchase your first home as soon as possible, you may want to increase your annual income. Consider picking up a weekend job or increasing your overtime hours at your current job. Automatically put all extra incoming money into your savings account to help quicken the growth of your future down payment. Think about doing a little freelance work to increase your total income as well.

Additionally, if you receive any extra cash, such as a tax return or birthday money from a family member, contribute that toward your savings. Money Manifesto recommended pretending that this extra income does not exist and automatically depositing the extra funds to help with your down payment fund.

Becoming a homeowner is a substantial milestone. Start saving for your down payment if you are interested in making the step toward owning your very own property.

*Article reprinted with permission from New American Funding. Licensed by the California Department of Business Oversight under the Residential Mortgage Lending Act – License #4131117 Broker Solutions Inc. dba New American Funding (NMLS #6606) Corporate Office is located at 14511 Myford Road, Suite 100, Tustin, CA 92780. 800.450.2010

Equal_Housing_OpportunityNAFlogoCorpNMLS#

For more information about loan options contact
Chris Smith NMLS# 253394 at Chris.Smith@nafinc.com
Bill FitzMaurice NMLS# 290216 Bill.Fitzmaurice@nafinc.com

Videolicious is a great marketing tool for Real Estate Agents

By Suzy Lins
April 21, 2015

Recently, a group of our professional REALTORS® attended a webinar by Alan Haburchak of Videolicious. Videolicious is an app you can use to create on the spot videos. It’s a great marketing tool for real estate agents to use to create a Listing Video, a “Come Check out my Open House” video or even a Client Testimonial video. It’s all done on your iPhone or iPad. Within about 15 minutes you can create the video and send it out to your social media sites, email to clients or upload to YouTube.

I know most of us don’t like how we look in photos let alone in videos. It took me a bit to get over how I looked on screen. But then I realized…that’s how I look. It was a blow to my ego but I got over it. If you can’t get over it and still don’t want to be on screen you can do a voice over of video clips and photos to create a marketing video.

I put together this short Videolicious video to show our agents just how easy it is and to motivate them to give it a try.

Our CENTURY 21 Discovery agents have access to an upgraded version of the app because of a partnership with Century 21 and Videolicious. Right now it’s only available on IOS products but there are plans for an Android version soon. Once you give it a try you’ll be amazed at how easy it is to use!

About the author: Suzy Lins is the Communications Director for CENTURY 21 Discovery. For more information about CENTURY 21 Discovery you may call (714) 626-2000.

Understanding Your FICO Score

By Courtney Lynch of New American Funding*
April 15, 2015
Originally published on March 24, 2015

Many of your financial investments depend greatly on one small three-digit number. Your FICO score dictates what kind of loans you receive and ultimately the purchase you can handle. It is important to be cognizant of your FICO score and know whether you need to make improvements to your credit.

What is a FICO score?
The National Association of Realtors noted that aFICO score determines your creditworthiness and it ranges between 300 and 850. Lenders consider borrowers with lower scores to be at a higher risk and those with higher scores to be at a lower risk. NerdWallet noted that your interest will correlate with your FICO score. Keeping your credit score low will save you money in the long run.

To determine how your credit score compares, speak with your financial adviser and know what is considered to be a good or bad score. Experian, a credit information service company, released its fifth annual credit study and 2014 showed the national average credit score increased two points from 664.

How is a credit score calculated?
The scoring model used by most lenders to determine your creditworthiness was developed by the Fair Isaac Corporation. There are a number of types of credit scores, but NAR reported most lenders prefer referencing FICO scores before providing a loan.

According to MyFICO, the scoring model uses five different categories to calculate a score. These include:

  • Types of credit used
  • New credit
  • Length of credit history
  • Amounts owed
  • Payment history

The types of credit used only accounts for 10 percent of how your FICO score is calculated while payment history makes a much larger and profound impact at 35 percent. Knowing which elements have the most profound effect on your score is important – especially when you want to improve your creditworthiness.

MyFICO also noted that your scores are not contingent upon your age, salary, current interest rates or whether you are enrolled in credit counseling.

Where is your score relevant?
When submitting a loan application, your credit score is always at the forefront of a lender’s mind. Given that creditworthiness determines how likely you are to pay back your loans, a good score is incredibly important when applying for a loan of any sort. Whether you are trying to obtain an auto or home loan, your FICO score can make or break you.

Freddie Mac reported that your credit is one of the most important and necessary elements of applying for a home mortgage.

What other factors may lead to a rejected loan application?
Opening multiple lines of credit and cosigning history are two additional elements lenders could potentially view as red flags, according to Bankrate.

Signing up for multiple credit cards in a short amount of time could alarm some lenders.

“That would raise some questions,” said Norm Magnuson, the vice president of public affairs for the Consumer Data Industry Association. “It could be an indicator of something that’s going on. I don’t think it’s in the best interest of any consumer to go out there and be a collector of credit lines.”

Cosigning is an additional factor that could impact whether you are approved for a loan. While you may not have to pay money when you help someone become approved for a loan, you may pay in other ways. When you cosign, you are also taking on that individual’s line of credit. If he or she does not have a good credit score, that can now be associated with your own creditworthiness.

In addition, if the individual you cosigned for decided not to make payments or turned them in late, these behaviors would count against you.

*Article reprinted with permission from New American Funding. Licensed by the California Department of Business Oversight under the Residential Mortgage Lending Act – License #4131117 Broker Solutions Inc. dba New American Funding (NMLS #6606) Corporate Office is located at 14511 Myford Road, Suite 100, Tustin, CA 92780. 800.450.2010

Equal_Housing_OpportunityNAFlogoCorpNMLS#

For more information about loan options contact
Chris Smith NMLS# 253394 at Chris.Smith@nafinc.com
Bill FitzMaurice NMLS# 290216 Bill.Fitzmaurice@nafinc.com

Apps for Home Buyers and Sellers

By Guest Blogger
March 31, 2015
This was originally published in the official blog of Century 21® on February 22, 2015*

When you are in the process of buying or selling a home, there are a lot of tasks that need to be handled. It can seem overwhelming, but with the right tools, you can stay organized and on top of everything that needs to be done. Luckily, there’s an app for that. Use these apps to help stay productive and organized during the home buying and selling process.

1. Evernote: Evernote is a note taking tool with lots of useful features that will help you stay organized on the go. Create separate notebooks for each step of the home buying process, for example: you could make notebooks for “Wants and Needs,” “Open House Reflections” “Financial Information,” “Closing Notes,” and more. You can even create bulleted lists, and attach photos and PDFs. Evernote syncs with all of your devices so you always have access to what you need.

2. Dropbox: Dropbox is essential for storing and organizing documents and paperwork. You have easy access to everything you need with the click of a button! Share documents or entire folders with your home buying team instantly so you’re always on the same page. Just like Evernote, Dropbox is able to sync with all electronics, giving you complete access to what you need!

3. CENTURY 21® Real Estate: Our app allows you to quickly find listings, sales associates, and nearby open houses. The app is GPS enabled so you can search listings specifically targeted for your location. You can also search based on price range, features, estimated taxes, square footage, and much more.

4. AroundMe: Learn about your potential new neighborhood. AroundMe[MH1] uses GPS to determine your location and in an instant, you’re able to see how close everything, from gas stations to movie theaters, is to the potential home.

These apps will help you stay organized and productive during your home buying or selling process.

*Article reprinted with permission of Century 21 Real Estate LLC.

Saving Money on Your Mortgage

By Shantell Lorraine Nicole Russell of New American Funding*
March 22, 2015
Originally Published on March 19, 2015

Everyone loves saving money and your monthly mortgage payment is no exception. When you apply for a home loan or are thinking about refinancing, there are a few things you should consider to keep your payments more affordable.

moneyNAFblog

Providing a larger down payment
While government-sponsored enterprises Freddie Mac and Fannie Mae are now offering loans with a 3 percent down payment option, paying more money up front can help keep your interest rates and monthly bill lower. Credit.com also noted that you can pay off your mortgage faster and this can leave you with the ability to access more spending money in the future.

Deciding on the right mortgage
There are a number of options available to individuals interested in purchasing a new home. The two main types of loans available are fixed- and adjustable-rate mortgages. According to Nerd Wallet, FRMs guarantee a specific interest rate over the course of the loan’s life. This is a great long-term option that you can easily organize your finances around. An ARM offers a lower introductory rate, but after a pre-determined amount of time the interest rate can fluctuate with the market.

Deciding on the best loan option for you depends on what type of loan fits your situation. You may not intend to use this mortgage toward your forever home. Perhaps you know that you are hoping to sell the house in the next five or 10 years. In this instance, an ARM with a lower interest rate would save you more money. However, if you are investing in a home you do not intend to move out of any time soon, an FRM might be a more dependable and ultimately more affordable option.

Lender-paid and borrower-paid mortgage insurance
Mortgage insurance provides protection for lenders if an individual is unable to pay back a loan. Zillow noted that there can be differences in the payments and rates associated with borrower-paid PMI and lender-paid PMI. Ensure that you consider the total monthly cost of PMI after tax deductions to decide which option is most cost-effective for you.

Shopping around for a mortgage
Before buying a new television, people usually check a few stores, browse the Internet and conduct a little research of their own. When you decide to purchase a new home, your hunt should be just as thorough, if not more intense to ensure you are getting the best deal. Bankrate noted that you can either shop for a loan yourself or hire a broker to do the hunting for you. If you decide to hire a broker, ask to speak with his or her clients before. They can offer you insight about the services he or she was able to provide for them.

You may also want to speak with your real estate agent about different lenders. He or she can direct you to a variety of options available and you can begin shopping for the best deal.

Consider paying extra
U.S. News and World Report suggested adding an extra payment each year. The additional payments are put toward your principal and help bring down the total amount you owe on your home and you will not have to pay as much interest on that total.

Making more payments on your mortgage now can ultimately save you more money on the total amount that you owe lenders. For example, if your current mortgage is $200,000 with a six percent interest rate on a 30-year FRM and you made one extra payment of $1,199 each year, you could not only save $47,000 but also cut five years off of your 30-year commitment.

Take a look at your current financial situation and determine whether this is a viable option for you.

Refinancing your mortgage to save money
While interest rates on home loans are low, you may find that refinancing is an increasingly appealing option. However, U.S. News and World Report noted that before you jump the gun and decide to refinance your home, you should calculate long term savings and the closing costs and fees you may accrue.

You should only move forward with this process if you have done the math and see that the savings make it worthwhile.

Another factor to consider is whether you are currently a good candidate for a new mortgage. Make sure that your credit score is healthy and you will qualify for a lower interest rate.
If you decide to refinance, remember that you should look at a few different lenders before committing. It is important that you find the best deal available.

Saving money is always helpful. Finding new ways to help with the cost of your mortgage can help your financial situation a great deal. Reach out to a professional, consider your options and make a plan to help you save money on your monthly payments.

*Article reprinted with permission from New American Funding. Licensed by the California Department of Business Oversight under the Residential Mortgage Lending Act – License #4131117 Broker Solutions Inc. dba New American Funding (NMLS #6606) Corporate Office is located at 14511 Myford Road, Suite 100, Tustin, CA 92780. 800.450.2010

Equal_Housing_OpportunityNAFlogoCorpNMLS#


For more information about loan options contact
Chris Smith NMLS# 253394 at Chris.Smith@nafinc.com
Bill FitzMaurice NMLS# 290216 Bill.Fitzmaurice@nafinc.com