Down Payments

A Real Estate Agent’s Guide to Working with the Lender

By Ryan World
October 2, 2026

Working with a qualified buyer involves more than getting a pre-approval letter and starting the home search. A good working relationship between the real estate agent and lender can help identify potential issues early, keep the transaction moving, and avoid surprises as you get closer to closing.

As the agent, you don’t need to know every detail of the lending process. But you should know which questions to ask and when. Here are some best practices to follow from your first meeting with a buyer all the way through funding.
Start With a True Pre-Approval

When you first meet with a potential buyer, ask if they have been pre-approved by a lender. If they say yes, don’t stop there. Dig a little deeper.

Ask whether they submitted income and asset documentation and whether the lender ran their credit. Some buyers believe they have been pre-approved when they have actually only been prequalified based on verbal information that hasn’t been verified yet.

That distinction matters. Once the lender verifies the buyer’s documentation, what the buyer actually qualifies for could look very different.

Before you invest time showing homes, make sure your buyer has gone through a thorough pre-approval process.

Know What Your Buyer Qualifies For

Once your buyer is pre-approved, communicate directly with the lender. Confirm the maximum sales price and the type of financing the buyer plans to use.

This is especially important because not every loan program works with every property.

For example, if your buyer is using FHA or VA financing and is interested in a condominium, you’ll want to determine whether that property meets the applicable financing requirements before getting too far into the process.

Knowing the details upfront can help you focus your buyer’s search on properties that are a realistic fit.

Before You Write the Offer, Call the Lender

You’ve found the house, and your buyer is ready to write. Before submitting the offer, call the lender again.

Give them the subject property address and property type to confirm the loan program works for that property.

This is also the time to discuss timelines. Ask how much time the lender anticipates needing for the appraisal, loan approval, and funding. Different loan programs and individual borrower circumstances can affect those timelines.

Don’t automatically plug standard dates into the offer. Talk to the lender first, so you know what is realistic for that particular buyer and loan.

Once You’re in Contract, Don’t Wait

As soon as you have a fully executed Residential Purchase Agreement (RPA), send it to the lender along with the Buyer Representation and Broker Compensation Agreement (BRBC), as applicable.

The sooner the lender has the necessary documentation, the sooner they can begin working toward the important financing milestones in the transaction.

And don’t assume that no news is good news. Stay in communication with the lender throughout the process.\

Check The Appraisal — Not Just the Value

When the appraisal comes in, there are a few important questions to ask.

The main ones being: Did the property appraise at an acceptable value? Did the appraisal come back “as is”?

If the appraisal is subject to repairs or other requirements, those items may need to be addressed before the loan can move forward. Finding that out quickly gives everyone more time to determine the next steps.

“Loan Approved” Doesn’t Mean You’re Done

Hearing that the loan has been approved is great news, but don’t assume that means the transaction is guaranteed to close.

Initial underwriting approvals typically come with conditions. Some may be relatively simple, such as providing additional documentation or a letter of explanation for an old address on a credit report. Others can be problematic, such as resolving a judgment or lien against the buyer.

Ask the lender whether there are any conditions that could be concerning or potentially affect the transaction timeline.

Keep Checking in Until Funding

As you approach closing, keep communicating with the lender and confirm the remaining milestones are on track.

Check on the status of the Closing Disclosure, final loan documents, and funding. There may also be mandatory waiting periods that need to be factored into the closing timeline.

The finish line may be in sight, but this isn’t the time to stop paying attention.

Final Thoughts

A good lender is an important part of your buyer’s real estate team, but a good agent doesn’t simply hand the buyer off to the lender and wait for updates.

Stay involved, ask questions, know the important deadlines, and keep the lines of communication open throughout the transaction.

When the agent and lender work together from pre-approval through funding, they’re much more likely to identify potential problems early, manage expectations, and keep the transaction moving toward a successful closing.
Ryan World is a Loan Originator with World Mortgage Group, a division of Golden Empire Mortgage, NMLS# 1164750. For more information about home financing you may contact him at (714) 569-3636 ext. 2 or email rworld@gemcorp.com.
What’s Going On With Mortgages?

By Joe Lins
July 21, 2024

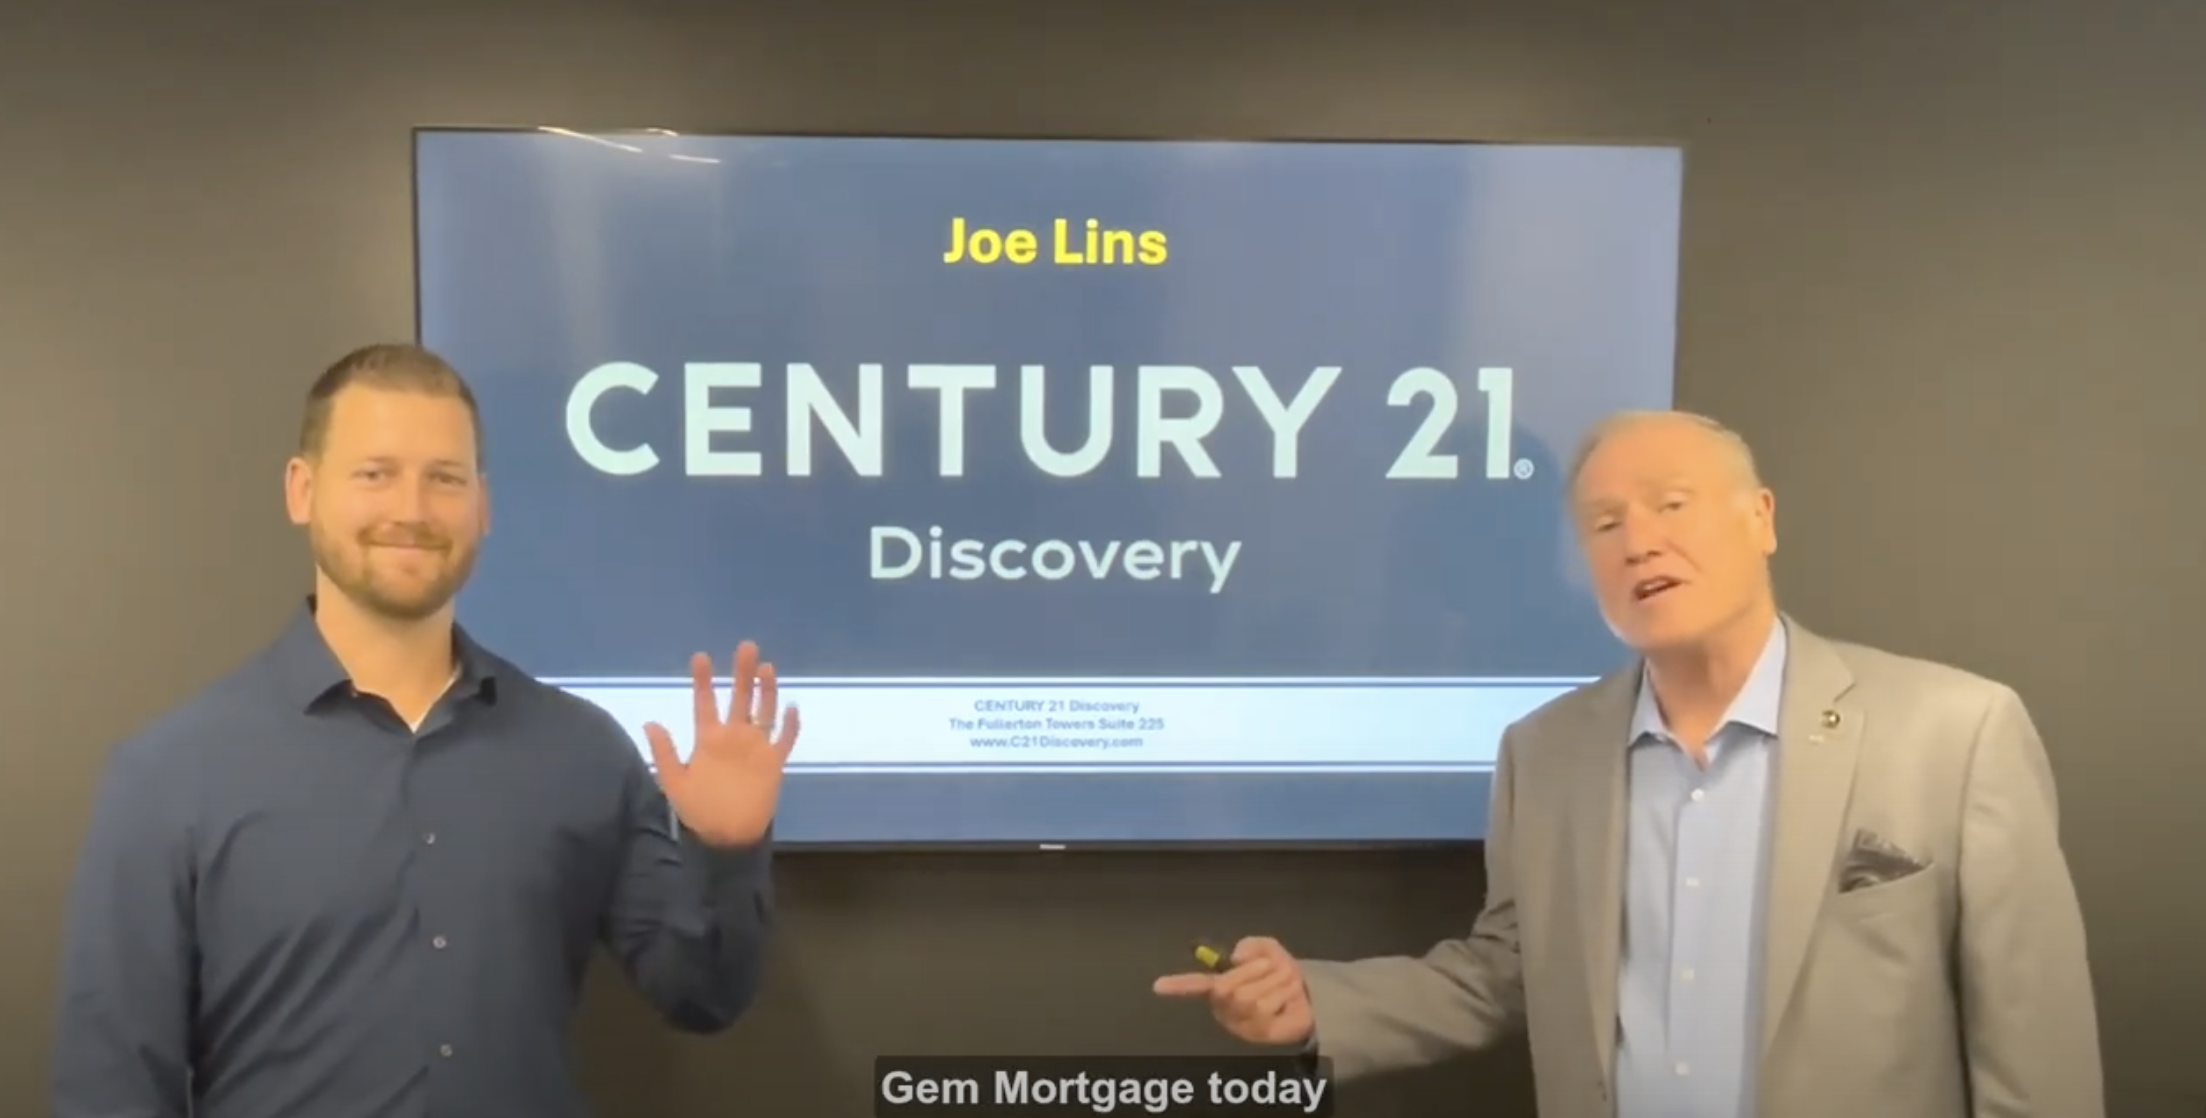
Recently, I had the pleasure of speaking with Ryan World from Gem Mortgage. We discussed the current mortgage landscape and what potential homebuyers need to know. For agents reading this, I encourage you to share this with your clients. Here’s a recap of what we covered in that conversation:

  • Different Loan Programs and Down Payments
  • Jumbo Loans
  • Current Interest Rates
  • Buying Now vs. Waiting to Buy
  • Having a Buyer Strategy
  • Why a Pre-Approval is Important

Different Loan Programs and Down Payments

Most people opt for conventional loans these days when it comes to loan programs. However, there are several options available:

  • VA Loans: Zero down payment.
  • FHA Loans: Requires a 3.5% down payment.
  • Conventional Loans: As low as 3% down unless it’s a high balance, which needs 5% down.
  • Jumbo Loans: Typically require around 20% down, though you can put less down for a higher interest rate.

Understanding Jumbo Loans

A jumbo loan is any amount exceeding the national conforming loan limit, which is currently $766,550 for Fannie Mae and Freddie Mac. These loans usually have better interest rates but are more challenging to qualify for.

Current Interest Rates

Interest rates are currently in the high sixes to low sevens. The market is quite volatile, and rates can change quickly based on economic indicators and Federal Reserve announcements. Recently, the Consumer Price Index released favorable news, causing a slight improvement in interest rates. However, market fluctuations are constant, and rates can shift based on new information.

Buying Now vs. Waiting for Lower Rates

A common question is whether to buy now or wait for interest rates to drop. Ryan suggests buying now, even with higher interest rates. The rationale is that if rates drop in the future, you can refinance. Waiting for lower rates could lead to increased home prices due to higher demand, making it more challenging to find a desirable property at a reasonable price.

The Importance of a Buyer Strategy

Buyers need a strategy, and one of the most crucial steps in buying a home is hiring the right REALTOR. A knowledgeable, competent real estate agent can guide you through the process to achieve your goals. Having a strategy in this fast-paced real estate market is important, and the right agent can help with this. Our CENTURY 21 Discovery agents are trained for exactly this!

Why Pre-Approval Matters

Getting pre-approved is essential. It helps you understand your budget, manage your expectations, and gives you confidence when working with your real estate agent as you start your home search. Knowing your financial standing upfront prevents disappointment and ensures you focus on homes within your price range.

Contact Information

Those interested in learning more about mortgage options or starting the pre-approval process can contact Ryan World at Gem Mortgage. His phone number is 714-569-3636, extension 2.  

Charge on!

You can watch the video of our conversation HERE.

You can listen to the conversation HERE.

Joe Lins

About the author: Joe Lins is President, CEO and Co-owner of CENTURY 21 Discovery. If you are interested in becoming part of the CENTURY 21 Discovery team or would like more information about our services, training and coaching we provide, contact Joe at 714.626.2069.

What Drives Mortgage Rates?

By Chris Smith
September 27, 2016

There are many things that drive mortgage rates available to Buyers. Some things are out of your control: National Employment Patterns, the Stock Market, actions of the Federal Reserve, natural disasters and geopolitical or global events.

Let’s focus on the things you CAN control to get the mortgage rate that fits your budget and allows you to get into that home you want.

what-drives-mortgage-rates

Credit Score
The better your credit score the lower your interest rate. Having a high credit score makes you a more favorable borrower in the eyes of the lender. First, find out what your credit score is. Then try improving your credit score before you start the loan application process. Talk to your loan consultant on ways you can improve your score.

Down Payment
There are a lot of low down payment options for borrowers. What you may not know is that if you increase your down payment on the home you are buying you can secure a lower interest rate. This can ultimately save you more money over the life of the loan.

Size of the Loan
The amount of money you borrow can impact the interest rate.  A larger loan amount will usually have a higher interest rate. The reason for this is because paying back a larger loan amount will likely take long and there is more at stake for the lending organization.

Type of Property and Occupancy
Loan pricing is slightly lower for single family homes compared to condominiums. Owner occupied loans also have lower rates than non-owner or investment properties.

The best way to understand all your options regarding interest rates is to talk to a loan consultant BEFORE you start your home search.

chrissmith2014


About the Author: Chris Smith is a Senior Mortgage Consultant (NMLS  #253394) with New American Funding. For more information about home financing you may contact him at 714.401.5921. 

Creatively Saving For A Down Payment For Your First Home

By Shantell Lorraine Nicole Russell of New American Funding*
June 8, 2015
Originally Published on June 4, 2015

moneyNAFblogRental rates are quickly rising making it more difficult to continue affording an apartment. While purchasing a home might seem like a less expensive option, saving for a down payment on a house is likely one of the more difficult aspects of becoming a home owner. One of the common standards for a down payment is 20 percent of the total value of the home. This can add up quickly and between mountains of student debt and the entry level job market, setting aside funds can be a challenge. However, with more lenient lending standards and a few tricks, you can start saving and become one step closer to owning a home of your own.

Understand the importance of a down payment
Before you begin planning to save up some extra cash, know how a down payment impacts your ability to become a homeowner. A down payment is the money you put toward a home right away. Zillow noted that the amount you can contribute upfront can impact the type of home mortgage you qualify for and ultimately how much house you can afford. In addition, your credit score and income also contribute to the home loan you ultimately receive.

This can help you determine how much you want to save for your future home. If you would like to purchase a more expensive home, but do not have the credit score or annual income to support higher monthly mortgage payments, providing a larger down payment can help ensure you still can afford a home more congruent to your preferences. Additionally, paying less than 20 percent of the total value of the home may mean that you need to also pay mortgage insurance on a regular basis.

Mortgage insurance is a way to back up a loan in case you are unable to make payments due to your financial circumstances.

Options for low down payments
If you are interested in acquiring a home without spending a great deal of money up front, Freddie Mac and Fannie Mae, government-backed lenders, both offer loans with 3 percent down payment options.

First-time homebuyers may qualify for these affordable options depending on their ability to provide specific information and meet certain standards to avoid underwriting mortgages. For example, Freddie Mac mandates that applicants can cover the closing costs as well as the full down payment agreement. Additionally, homebuyers must enroll in a borrower education program similar to the one offered by Freddie Mac. Fannie Mae also implemented similar requirements to combat lending money to an unsuitable candidate who is unable to afford a home.

Techniques for saving money 
After deciding how much money you wish to save for a down payment, USA Today recommended setting up automatic contributions to your savings account every pay period. This ensures that you are not tempted to dip into your pot and spend any of your money before putting it into your savings account. In addition, automatically sending money to your savings account is a great idea as long as you have properly budgeted for a specific amount to be contributed regularly.

Developing an adjusted budget to accommodate your new efforts is an important step to the process. Decide how much money you need for your expenses, like rent, bills, food and any debt. Then allot additional money for recreational spending.

The Daily Finance also noted it might be a smart idea to keep your savings safely stored away somewhere that it is more difficult for you to access. Consider starting a high-yield savings account or CD.

Know where to make cuts
There are a number of frivolous expenses that can add up and prevent you from saving for a down payment on a house. Below are some extra expenses you might consider reducing to help increase your savings:

  • Making daily coffee shop runs
  • Eating out regularly
  • Going out to the bars
  • Going to the movies
  • Taking weekend trips
  • Having regular manicures or pedicures
  • Attending concerts, plays and other performances


Add additional income

If you are ready to purchase your first home as soon as possible, you may want to increase your annual income. Consider picking up a weekend job or increasing your overtime hours at your current job. Automatically put all extra incoming money into your savings account to help quicken the growth of your future down payment. Think about doing a little freelance work to increase your total income as well.

Additionally, if you receive any extra cash, such as a tax return or birthday money from a family member, contribute that toward your savings. Money Manifesto recommended pretending that this extra income does not exist and automatically depositing the extra funds to help with your down payment fund.

Becoming a homeowner is a substantial milestone. Start saving for your down payment if you are interested in making the step toward owning your very own property.

*Article reprinted with permission from New American Funding. Licensed by the California Department of Business Oversight under the Residential Mortgage Lending Act – License #4131117 Broker Solutions Inc. dba New American Funding (NMLS #6606) Corporate Office is located at 14511 Myford Road, Suite 100, Tustin, CA 92780. 800.450.2010

Equal_Housing_OpportunityNAFlogoCorpNMLS#

For more information about loan options contact
Chris Smith NMLS# 253394 at Chris.Smith@nafinc.com
Bill FitzMaurice NMLS# 290216 Bill.Fitzmaurice@nafinc.com